Employment

Company Vehicle Policy | FCRA & FMCSA 392.82 Ready

Lawyer-drafted company vehicle use and driving policy built to FCRA 1681b MVR consent rules and FMCSA 392.80 device bans. All 50 states. Word and PDF.
4.5/526 reviews50 000+ downloadsInstant download
Share

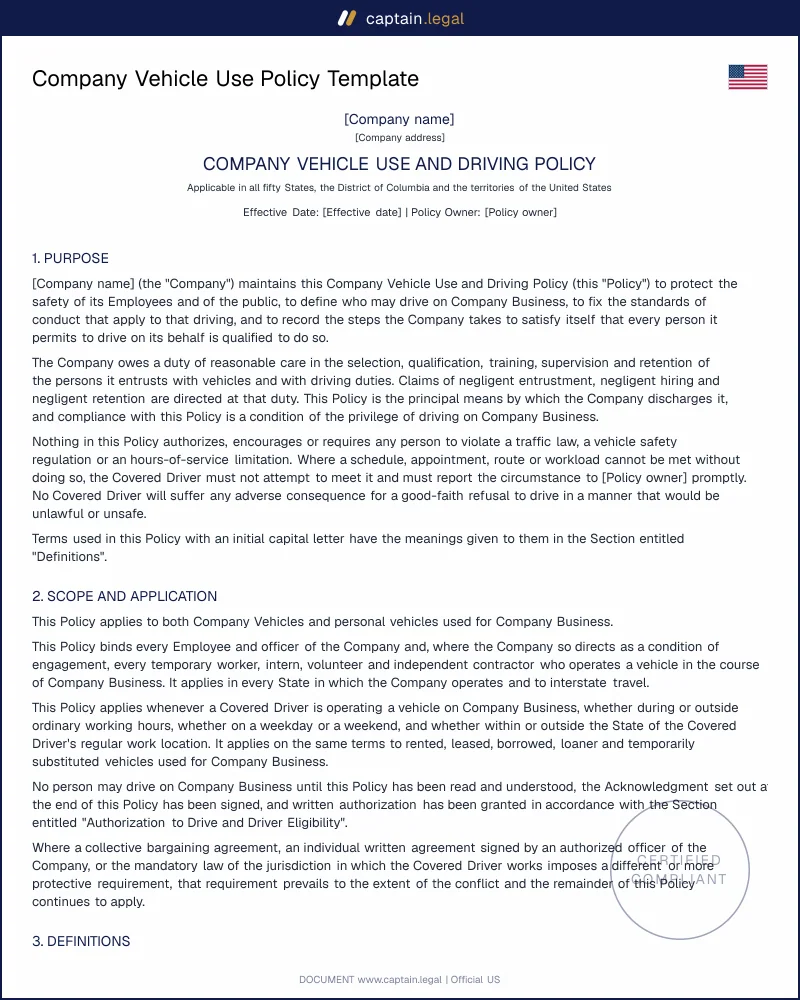
A company vehicle use and driving policy is the written rulebook that decides who may drive a company owned or leased vehicle, how that vehicle may be used off the clock, and what a driver must do in the hours after a collision. Employers who put staff behind the wheel carry two separate exposures: respondeat superior for crashes in the course of employment, and negligent entrustment for handing keys to someone whose record should have disqualified them. One is hard to avoid. The other is a paperwork problem, and it is the one plaintiff lawyers reach for first. This template covers MVR check consent, personal use limits, distracted driving bans, accident reporting and insurance verification, and adapts to all 50 states.

Compliant

2026 Legislation

50,000+ clients

trust us

Affordable

From $4.90 / doc

Secure payment

Instant download

Company Vehicle Policy | FCRA & FMCSA 392.82 Ready

Secure payment

Fill in the template

What is a company vehicle use and driving policy?

A company vehicle use and driving policy is an employer issued document setting the conditions under which an employee may operate a vehicle for work, whether that vehicle is company owned, leased, or the employee's own car driven on company business. It combines three things smaller employers usually keep apart: eligibility screening, operating rules, and post-incident procedure. The acknowledgment block at the end is what turns it from an internal memo into evidence, because it records that the driver received the rules, consented to a periodic motor vehicle record check, and accepted the personal use limits that drive the tax treatment of the benefit.

The document is not a fleet safety manual, which is operational: maintenance intervals, pre-trip inspections, load securement, nor a vehicle allowance agreement setting a stipend or a mileage rate. The driving policy sits above both and answers the liability questions: who is an authorized driver, what disqualifies them, and who reports the accident. Most employers fold it into the employee handbook template for US employers as a chapter with its own signature page.

2

When do you need this document?

The obvious case is a service fleet: vans, pickups, box trucks, anything with a logo on the door. Once a vehicle carries branding, every complaint from another motorist becomes a call to your dispatcher, and a written policy turns that call into a documented coaching event. The second trigger is the take home car for a sales team, which spends most of its hours outside working time. That is where personal use, spousal drivers and weekend mileage become live questions.

Insurance renewal is the third. Underwriters ask whether the applicant maintains a written driver qualification standard and how often abstracts are refreshed, and a stated review interval usually moves the quote. A fourth scenario involves no company vehicles at all: staff running errands or visiting clients in their own cars create non-owned auto exposure that most small business policies leave uninsured until somebody asks.

Two edge cases justify closer attention. The first is the employee who lets a spouse drive the take home vehicle for a grocery run: without a clause naming that as unauthorized use, an owner liability statute attaches with no argument available. The second is the driver whose commercial license quietly downgrades because a medical certificate lapsed and nobody looked.

3

Key clauses included in our template

  • The authorized driver and eligibility clause names who may operate a company vehicle and fixes the disqualifying thresholds: moving violations in a rolling period, any impaired driving conviction within a stated lookback, license suspension, refusal of a chemical test. It also states the minimum driver age required by your commercial auto carrier, frequently stricter than state licensing law.
  • The MVR consent and periodic review clause captures written authorization to obtain and re-check the abstract, drafted to sit alongside the standalone FCRA disclosure rather than absorb it. It fixes the review interval and obliges the driver to self report any citation or license action promptly.
  • The personal use clause defines permitted scope precisely, because the definition drives payroll. Options run from strict business only, to commuting plus de minimis personal use, to full personal use with imputed income. Passengers, out of state travel and family members are addressed here.
  • The distracted and impaired driving clause bans hand held phone use outright rather than tracking the patchwork of state rules, and covers prescription medication carrying a driving warning. A blanket ban removes any argument that the company tolerated conduct lawful in one state.
  • The accident reporting clause sets the sequence: secure the scene, call emergency services, notify a named company contact within a fixed window, exchange information, photograph, decline to discuss fault.
  • The insurance and property clause requires proof of personal coverage at stated minimum limits for staff driving their own cars, allocates tolls, fuel cards and parking tickets, and obliges return of keys at separation. Read it with the expense reimbursement policy covering mileage and fuel cards.
4

State-specific considerations

California attaches owner liability by statute. Under Cal. Veh. Code §17150, the owner answers for injury caused by anyone driving with permission, express or implied, independently of any employment relationship. Section 17151 caps that liability, but the cap does nothing for the negligent entrustment count filed alongside it. Cal. Veh. Code §23123.5 prohibits holding a phone while driving at all, so a hands free carve out written for another state will not travel. Staff driving personal cars are separately owed indemnity under Labor Code §2802.

New York is the harshest jurisdiction for fleet owners. VTL §388 imposes vicarious liability on the owner for negligence by any permissive user, with no statutory cap. The Third Department held in Williams v J. Luke Constr. Co. that breaching an internal driving rule does not by itself withdraw permission, since a rule about how a vehicle is operated is not a restriction on who may operate it. Drafting matters enormously here: the clause must restrict the class of authorized drivers, not merely list prohibited behaviors. Portable devices are separately banned by VTL §1225-c and §1225-d.

Texas has no permissive use statute, so plaintiffs proceed on negligent entrustment under Schneider v. Esperanza Transmission Co., which requires entrustment to an unlicensed, incompetent or reckless driver the owner knew or should have known to be so. The MVR file then becomes the whole case. Electronic messaging while driving is banned statewide by Transportation Code §545.4251.

Florida applies the dangerous instrumentality doctrine, dating to Southern Cotton Oil Co. v. Anderson, which makes the owner strictly liable for negligent operation by anyone entrusted with the vehicle. Limited caps exist for lessors under Fla. Stat. §324.021(9)(b), but an employer owner gets none of that protection. Hand held use is a primary offense under Fla. Stat. §316.305.

Illinois bans hand held devices at 625 ILCS 5/12-610.2 and adds a trap for employers rolling out telematics. Driver facing cameras running facial recognition or other biometric identifiers fall under the Biometric Information Privacy Act, 740 ILCS 14, which requires a written release before collection and carries a private right of action. Deploying an AI dash cam fleet wide without an Illinois consent addendum is the most expensive drafting oversight in this area. Keep the policy consistent with your remote work agreement setting out home office and travel expectations.

5

How to fill out this company vehicle use policy

You start by identifying the employer entity and the states where drivers are based, because that answer loads the correct hands free rule, owner liability language and reimbursement obligation. Next you describe the fleet: company owned vehicles, leased units, pool cars, employee owned cars used for work, or a combination. The questionnaire then asks whether any driver operates a vehicle meeting the commercial motor vehicle threshold, and adds the FMCSA clauses where the answer is yes.

The eligibility section is where you set your own risk tolerance: the lookback period for violations, the number of at fault accidents that triggers review, and whether an impaired driving conviction is a permanent bar. Check these against your commercial auto declarations, since an insurer standard stricter than your policy leaves a gap. You then select the personal use model, which pulls in matching language on imputed income. The last steps cover accident reporting contacts and the acknowledgment page, and the document arrives with a separate MVR consent form so the FCRA disclosure stays standalone. Employers building a broader contract stack usually pair it with the business agreement templates for vendors and service providers.

6

Common mistakes to avoid

The most common failure is a policy that exists but was never signed. An unsigned policy in a personnel file proves nothing about notice, and opposing counsel will argue the rules were aspirational. The second is stale screening: an abstract pulled at hire and never again is worse than none at all, because the file shows the company knew record checks mattered and then stopped. A close third is the mismatch between policy and insurance declarations, where a rule allowing drivers at twenty against a carrier requiring twenty-one produces an uncovered loss the day it matters.

The subtler mistakes cluster around enforcement. A company that documents three phone use violations and disciplines none has manufactured evidence of tolerance, and its own records then work against it. Selective enforcement is more dangerous than no enforcement. Employers also write a personal use clause and then never report imputed income, which turns a routine payroll audit into a multi-year assessment.

Key takeaways

Liability

Screen drivers or own negligent entrustment

When an employee crashes on the job, the company can face vicarious liability, but plaintiffs often lead with negligent entrustment: you handed over keys to someone you knew or should have known was unsafe. The policy’s eligibility rules and periodic motor vehicle record (MVR) checks are designed to show you did the screening, set disqualifiers, and enforced them before a jury ever sees the driver’s history.

FCRA Consent

MVR consent must be standalone paperwork

Pulling a driving record is not just a safety step; it is regulated. If you use a screening vendor, the MVR can be treated as a consumer report, triggering the Fair Credit Reporting Act. Under 15 U.S.C. §1681b(b)(2), the disclosure must be a standalone document, not tucked into an application, and the employee’s written authorization has to come before the pull.

FMCSA Rules

Ban texting and handheld phones for CMVs

If your drivers operate commercial motor vehicles, federal distracted-driving rules apply on top of your internal policy. FMCSA bars texting at 49 CFR §392.80 and handheld mobile phone use at §392.82, and the carrier can be cited or sued for allowing it, not just the driver. The template pairs clear device bans with reporting procedures so enforcement is not optional after an incident.

Frequently Asked Questions

Yes, once the employee signs the acknowledgment. The document is an employer issued policy rather than a negotiated contract, and it takes effect through notice and acknowledgment the way a handbook policy does. The MVR consent portion is different: that is a standalone authorization required by the FCRA, with independent force as consent to obtain a consumer report. Keep the signed acknowledgment in the personnel file and the consent form separate from it.

Not safely. State abstracts are governed by the Driver's Privacy Protection Act, which permits access for employment verification but exposes you to a private right of action where the purpose does not fit. If you use a screening vendor, the FCRA applies and written authorization is mandatory before the pull, following a disclosure that appears on its own document. Build the consent into onboarding and phrase it to cover periodic re-checks for the duration of employment.

The policy is delivered in Word and PDF. The Word file is the working copy, so your HR lead can adjust violation thresholds, insert the fleet contact name, or remove clauses that do not apply. The PDF is the distribution and signature copy, formatted for printing and for filing in a personnel system.

The template requires an immediate call to the designated company contact from the scene once anyone injured has been attended to, followed by a written report within one business day. That timing is not arbitrary. Commercial auto carriers impose prompt notice conditions, and delayed reporting is one of the few grounds on which a defense can be prejudiced. Post accident testing is also time sensitive: the federal windows for regulated drivers are measured in hours rather than days.

Annual is the common standard and the interval insurers expect to hear. Employers with drivers on the road most of the day, or carrying passengers, often move to a semiannual cycle or subscribe to continuous monitoring that pushes an alert when a new violation posts. Whatever interval you choose, write it in and then honor it: a stated interval you miss is more damaging than a discretionary standard.

Yes, and that section matters more than most employers expect. The template extends eligibility screening to staff using personal vehicles on company business, requires proof of personal liability coverage at stated minimum limits, and flags the states where reimbursement is a statutory obligation. Related instruments sit in the complete catalog of US legal templates if you also need a standalone mileage document.

4.5/5

26 verified reviews · 50 000+ downloads

Company Vehicle Policy | FCRA & FMCSA 392.82 Ready
  • Immediate access to the document
  • PDF + Word download
  • Compliant with 2026 legislation
  • Reviewed by lawyers
Fill in the template
Secure payment
Updated on September 6, 2026

You might also like

Background Check Disclosure & Authorization
Sales Commission Agreement