Personal

Binding Death Benefit Nomination | SIS Act & Reg 6.17A

Binding death benefit nomination drafted to reg 6.17A SIS Regulations: dependant declaration, two-witness rules, 3-year lapsing and SMSF non-lapsing.
4.5/5— 14 reviews50 000+ downloadsInstant download
Share

Superannuation rarely passes under your will. It sits in a trust, and after you die the fund trustee decides who receives it, unless you have taken that discretion away. A binding death benefit nomination does exactly that: a written direction under section 59(1A) of the Superannuation Industry (Supervision) Act 1993 and regulation 6.17A of the SIS Regulations 1994, naming who must receive your super and in what proportions. This template produces the nomination itself plus a companion letter of wishes for the trustee, with the two-witness attestation block, the dependant declaration and the three-year lapsing date already drafted. It covers members of APRA regulated funds and, where the deed allows, self managed funds.

Compliant

2026 Legislation

50,000+ clients

trust us

Affordable

From $4.90 / doc

Secure payment

Instant download

Binding Death Benefit Nomination | SIS Act & Reg 6.17A

Secure payment

Fill in the template

What is a binding death benefit nomination?

A binding death benefit nomination converts a trustee discretion into a trustee obligation. Without one, the fund looks at your account, at any preferred nomination you left, at your relationships on the day you died, and decides for itself. With a valid notice on file, regulation 6.17A(4) leaves no room: the trustee must pay the people you named, in the shares you set.

Two documents get confused with it. A reversionary pension nomination attaches to an income stream and continues that pension to a nominated beneficiary, usually a spouse, on different tax timing. A preferred nomination is a wish and nothing more. Your will is a third thing again, because super is trust property and falls outside your estate unless the benefit is directed to your legal personal representative. That phrase is the bridge: it brings the money into the estate so it follows your last will and testament drafted to state succession law. Nominating "my estate" in loose wording has failed in court more than once, so the template uses the statutory term.

When do you need this document?

Blended families are the standard trigger. A second spouse and adult children from a first marriage rarely agree about super, and a trustee left to decide often splits the benefit in a way nobody wanted. Size is the second trigger: with insurance inside super counted, a modest account can pay out several hundred thousand. Members of a self managed fund have a sharper reason: control passes on death to the surviving trustee or director, who then exercises the discretion over your benefit.

You also need one when the benefit should reach your estate rather than a person directly, usually to fund a testamentary trust for young children or for a beneficiary with a disability. Nominating the legal personal representative is the only route there. Two edge cases deserve a flag. If you are in a de facto relationship your fund has never been told about, a nomination spares your partner an evidentiary fight, and a binding financial agreement under section 90B of the Family Law Act often sits beside it in the same file. Where family law proceedings are on foot, reg 6.17A(4A) lets the trustee ignore your nomination if a court order restrains payment.

Key clauses included in our template

  • The fund identification block records the fund name, the trustee, your member number and the service address the notice goes to. A nomination that never reaches the trustee is not in effect, so the template keeps a record of where and when you lodged it.
  • The beneficiary schedule names each recipient, states the relationship that makes them a dependant and sets the share as a whole percentage. Reg 6.17A(4)(b) demands proportions that are certain or readily ascertainable, so the schedule totals 100 per cent and carries a substitution direction if a nominee dies before you.
  • The dependant declaration records the section 10 or section 10A category relied on for each person named. Where you rely on interdependency or financial dependency, the trustee wants proof, usually a statutory declaration under the Statutory Declarations Act 1959 from someone who knew the household.
  • The lapsing or non-lapsing election sets the life of the notice, and where an SMSF deed authorises non-lapsing wording the template records the clause relied on. Non-lapsing wording with no deed power behind it is worth nothing.
  • The revocation clause cancels every earlier nomination and addresses any reversionary pension already running, since a reversionary stream and a nomination pointing elsewhere collide at the worst moment.
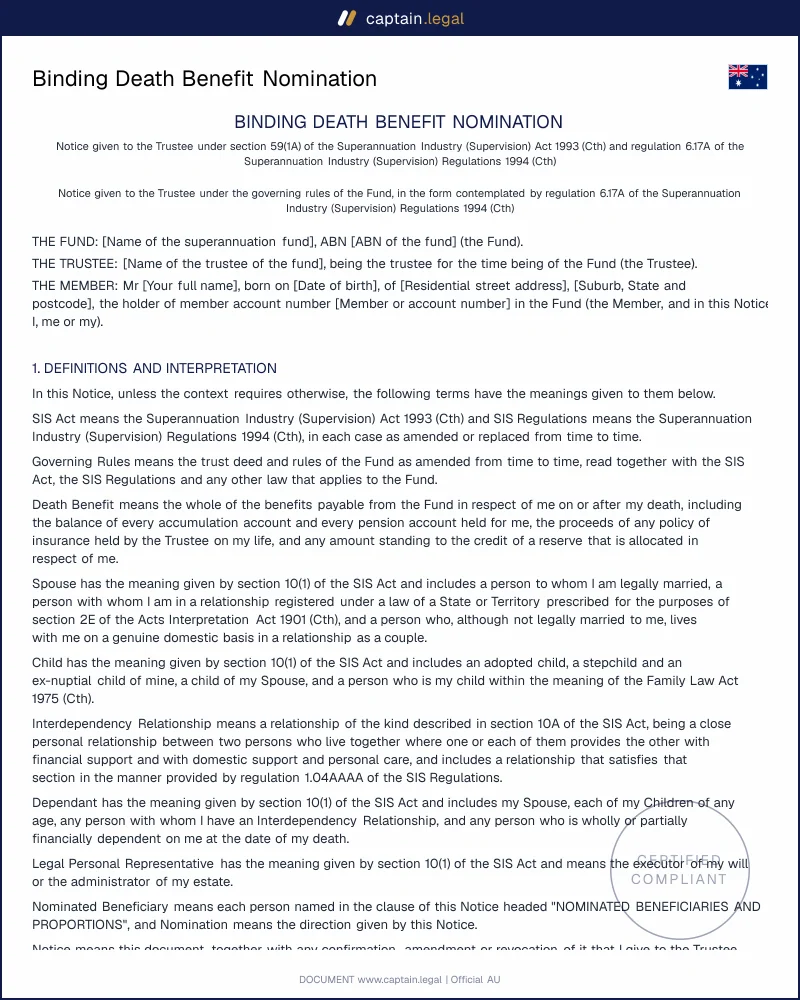
  • The witness attestation block reproduces the wording required by reg 6.17A(6)(c), with separate dating lines for you and both witnesses. The letter of wishes sits outside the nomination and speaks to your trustee and executor about your reasoning and any uneven shares.

State and territory considerations

Superannuation is Commonwealth law, so the nomination rules read the same in Perth and in Hobart. What changes is what happens around the benefit once it is paid, and family provision law is where the difference bites.

New South Wales is the outlier that matters. Under Chapter 3 of the Succession Act 2006 (NSW), a court can designate property that never formed part of the estate as notional estate and order provision out of it, and superannuation death benefits have been caught that way. A NSW nomination faces a family provision claim in a way it does not anywhere else, which argues for paying a dependant directly.

Victoria produced Wooster v Morris [2013] VSC 594, where a surviving trustee ignored a valid binding nomination and the daughters spent years enforcing it. Under the Powers of Attorney Act 2014 (Vic), an attorney appointed by an enduring power of attorney drafted to your state's rules who signs a nomination naming themselves enters a conflict transaction, and most funds refuse it.

Queensland gave the country its two teaching cases. In Munro v Munro [2015] QSC 61 a nomination favouring the trustee for the estate failed, because a trustee of a deceased estate is not the legal personal representative. In Donovan v Donovan [2009] QSC 26 the nomination missed the fund deed's own conditions.

Western Australia supplied Hill v Zuda Pty Ltd, which travelled up through the WA courts before the High Court settled the SMSF question, and Ioppolo & Hesford v Conti [2013] WASCA 25 on a surviving trustee's rights. De facto property matters in WA run under the Family Court Act 1997 (WA), not the federal regime.

South Australia, Tasmania, the ACT and the Northern Territory each run their own family provision statutes, from the Inheritance (Family Provision) Act 1972 (SA) to the Family Provision Act 1970 (NT). None carries a notional estate power, so a benefit paid straight to a nominated dependant stays beyond the reach of an estate claim.

How to fill out your binding death benefit nomination

You start by telling the form whether your super sits in an APRA regulated fund or a self managed fund, because that single answer changes everything downstream. For an APRA fund the document is built to reg 6.17A and defaults to a three-year term. For an SMSF it asks for the deed clause that authorises binding nominations and offers non-lapsing wording.

Fund details, member number and the service address come next, then the beneficiaries. For each one you select the dependency category, which generates the declaration wording, and you enter a percentage; the schedule will not close anywhere other than 100 per cent. Choosing the legal personal representative option inserts the statutory phrase for you, so the benefit reaches your estate without the wording that sank Munro.

The last step builds the execution pack: an attestation block with dating lines for you and both witnesses, a short sheet on who cannot witness, and the letter of wishes, which you sign but do not have witnessed. Download both in Word and PDF, sign in front of your two witnesses on the same day, then lodge the original with the trustee.

Common mistakes to avoid

The witnessing block causes more failures than every other part of the document combined. A beneficiary cannot witness, so the adult daughter you nominated cannot sign even though she drove you there, and both witnesses must date their declaration on the day you signed yours. The beneficiary list is the next casualty: a parent, a sibling, a friend or a former spouse is not a dependant under section 10, and a nomination in their favour is not binding however carefully it was witnessed. Shares totalling 98 per cent fail on the same logic.

Then come the slow failures. A lapsing nomination expires quietly three years after signing and nobody discovers it until a claim is made, so calendar the renewal and use the short confirmation route in reg 6.17A(5). Signing the notice and leaving it in a drawer has the same result: it has to reach the trustee to be in effect. After a separation people rewrite the will and forget the super, which is how an ex-spouse collects a death benefit years later; if you are working through a separation agreement under the Family Law Act 1975, the nomination belongs on the same checklist. Do not assume your attorney can sign a nomination for you, because the law is unsettled and most funds decline it.

Key takeaways

SUPER AND WILLS

Your super usually bypasses your will

Superannuation sits in a trust, so the fund trustee normally decides where it goes after death. A valid binding nomination under section 59(1A) of the SIS Act and regulation 6.17A(4) makes the trustee pay the named recipients in the stated shares. To send it through the estate, use the statutory term legal personal representative.

SIGNING RULES

Two independent witnesses, same date

An APRA fund nomination must be written, signed and dated by the member in front of two witnesses. Each witness must be over 18 and not named in the nomination. Their declaration should carry the same date as the member's signature; a mismatch is a common reason for rejection. Under regulation 6.17A(7), it lapses after three years.

BENEFICIARIES

Only eligible recipients can be named

The nomination can bind the trustee only if every recipient is a dependant or the legal personal representative, and the percentages are certain. Dependants include a spouse, de facto partner, child, financial dependant or interdependency partner under the SIS Act. Tax can still bite: an independent adult child may receive a taxed death benefit. For SMSFs, the deed sets the rules.

Frequently Asked Questions

Yes, where it meets the four conditions in regulation 6.17A(4). Everyone named must be a dependant or your legal personal representative, the shares must be certain, the form must be witnessed correctly, and the notice must still be in effect. Satisfy all four and the trustee has no discretion left. Miss one and the document drops back to a wish. Self managed funds answer to the deed instead, not the regulation.

Three years from the day you first signed it, or from the day you last confirmed or amended it, under regulation 6.17A(7), or sooner where the fund's rules fix a shorter period. Renewal is lighter than starting again: regulation 6.17A(5) lets you confirm an existing notice with a written statement you sign and date, with no witnesses needed.

Only where your fund's governing rules allow it. Many large funds offer it, and self managed funds have broad freedom because regulation 6.17A does not apply to them. A deed that is silent, or that requires nominations to comply with the superannuation law, can turn non-lapsing wording into a three-year notice.

Your spouse or de facto partner, your children of any age including stepchildren, anyone financially dependent on you, anyone in an interdependency relationship with you under section 10A, and your legal personal representative. The list is closed. Parents, siblings, friends and charities cannot be nominated directly, so the way to reach them is to direct the benefit to your legal personal representative.

Two people who have each turned 18 and who are not mentioned anywhere in the notice. They do not need to be lawyers or justices of the peace: neighbours and colleagues are fine. Both must watch you sign, then sign and date their own declaration on that same date. Anyone named in the document is disqualified, a substitute beneficiary included.

The nomination and the letter of wishes arrive as an editable Word file and a print ready PDF. Most members print the PDF for signing and keep the Word version for the next renewal. If your fund insists on its own branded form, the template is the drafting record you transcribe from. Related estate documents sit in the full catalogue of Australian legal templates.

Slower than most families expect. ASIC reviews of death benefit claims handling found wide variation between trustees, with the strongest fund closing nearly half its claims inside 90 days and the weakest a small fraction of that. A valid nomination is the biggest single accelerator, because the trustee no longer has to investigate relationships or invite competing claims. Identity checks, the death certificate and probate still take time.

4.5/5

14 verified reviews · 50 000+ downloads

Binding Death Benefit Nomination | SIS Act & Reg 6.17A
  • Immediate access to the document
  • PDF + Word download
  • Compliant with 2026 legislation
  • Reviewed by lawyers
Fill in the template
Secure payment
Updated on September 13, 2026

You might also like

Statutory Declaration Template
Family Loan Agreement Australia