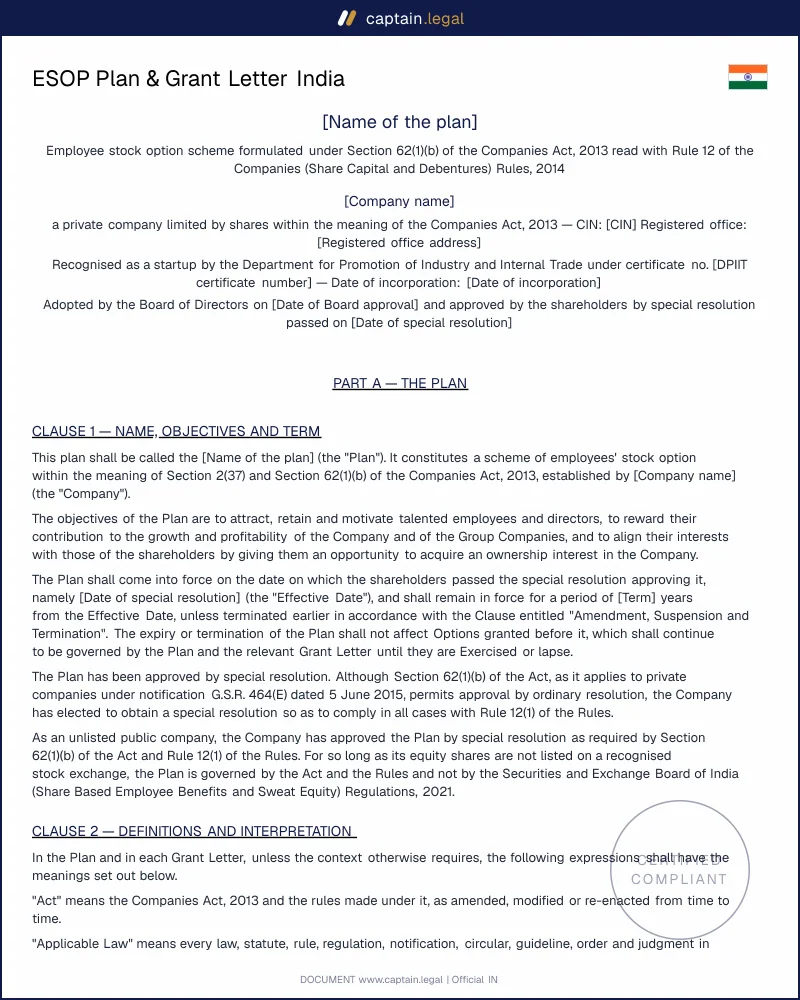
Private limited companies should pass the shareholder approval as a special resolution and file it in Form MGT-14, for the reasons set out above. Each allotment on exercise then goes to the Registrar in Form PAS-3 within 30 days. A private company that is not a small company must issue exercised shares in dematerialised form under Rule 9B of the Companies (Prospectus and Allotment of Securities) Rules 2014. Every option holder therefore needs a demat account before exercising. Small companies remain free to issue physical share certificates.
Unlisted public companies have no exemption to rely on, so the special resolution is mandatory. Many are preparing a listing, and their scheme must be ratified by shareholders after the IPO under the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations 2021 before any fresh grant. Regulation 9A, in force since 8 September 2025, lets an employee identified as promoter in the draft offer document keep options granted at least one year before filing. Grants made inside that year lose the protection. The planned filing date should therefore shape the grant calendar.
Foreign-owned Indian subsidiaries also answer to the Foreign Exchange Management (Non-debt Instruments) Rules 2019. Options to employees resident outside India are allowed within the company's sectoral cap. Each issue is reported to the RBI in Form ESOP within 30 days. Grants to persons from a country sharing a land border with India may need prior government approval. When the foreign parent's global plan is used instead, the Indian employer still carries the withholding obligations on the perquisite.
Stamp duty follows the place of execution, not the registered office. A grant letter signed in Mumbai is stamped under the Maharashtra Stamp Act 1958, one signed in Bengaluru under the Karnataka Stamp Act 1957, and one signed in Delhi under the Indian Stamp Act 1899 as applied there. The issue of shares on exercise is a separate instrument, charged at a uniform national rate since the Finance Act 2019 amendments took effect on 1 July 2020. An unstamped grant letter is inadmissible in evidence until the duty and penalty are paid. Our incorporation and governance templates for Indian companies apply the same statutory references.