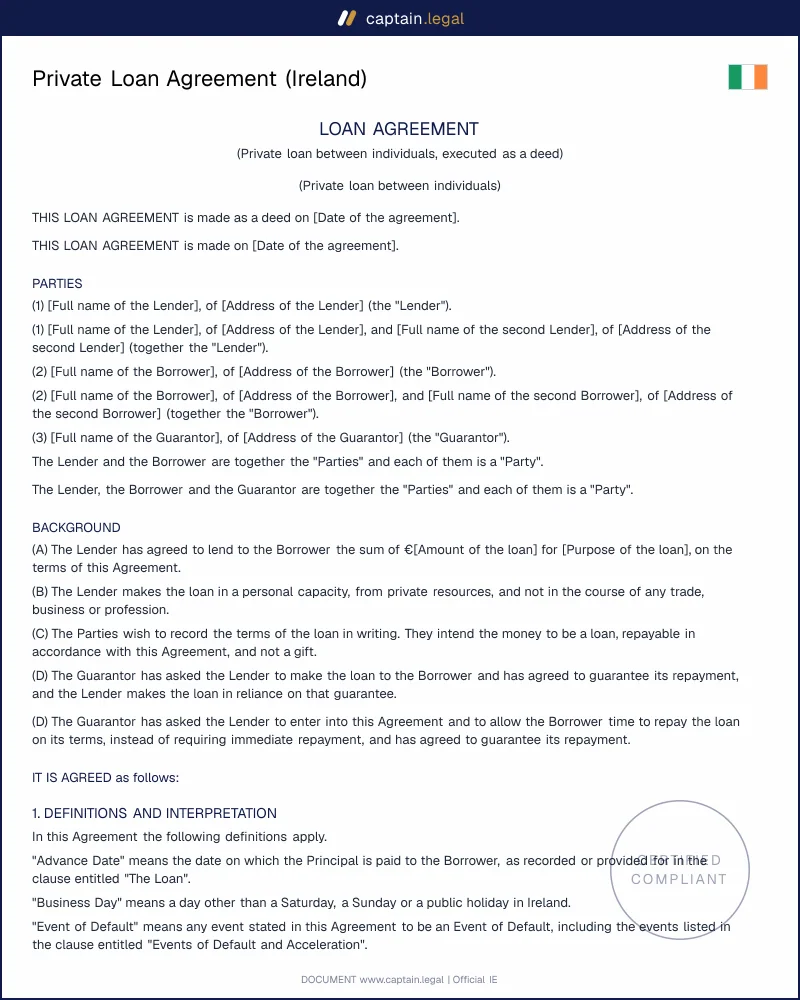
The opening clauses define the Principal, the Advance Date and the Lender Account and state the purpose. The money is either paid by transfer before a latest date, with the Borrower free to end the agreement if it never arrives, or acknowledged as received on a stated date. Interest is optional. A fixed rate is simple interest calculated daily on a 365-day year, payable with each repayment of principal and at least once every twelve months, and it never runs for a period before signature.
Repayment follows one of three models: regular instalments, one sum by a fixed date, or repayment on demand after a notice period you choose. In the on-demand version, nothing falls due until a written demand has been received. Early repayment is always allowed without a fee, and partial prepayments reduce the last instalments first. A statement of the balance, which the Lender may send up to twice a year, must be signed or disputed by the Borrower within 14 days; once signed, it is a fresh written acknowledgement of the debt.
Default works in two stages. A payment more than the agreed number of days late is an Event of Default, but the whole loan only becomes due after a written Acceleration Notice gives the Borrower a further 14 days to put things right. Late-payment interest is optional and replaces, rather than adds to, the normal rate. The guarantee, when selected, makes the guarantor liable to pay within 14 days of a written demand and requires his or her written consent to any increase in the principal or rate. Final clauses cover death, written release, notices and mediation.