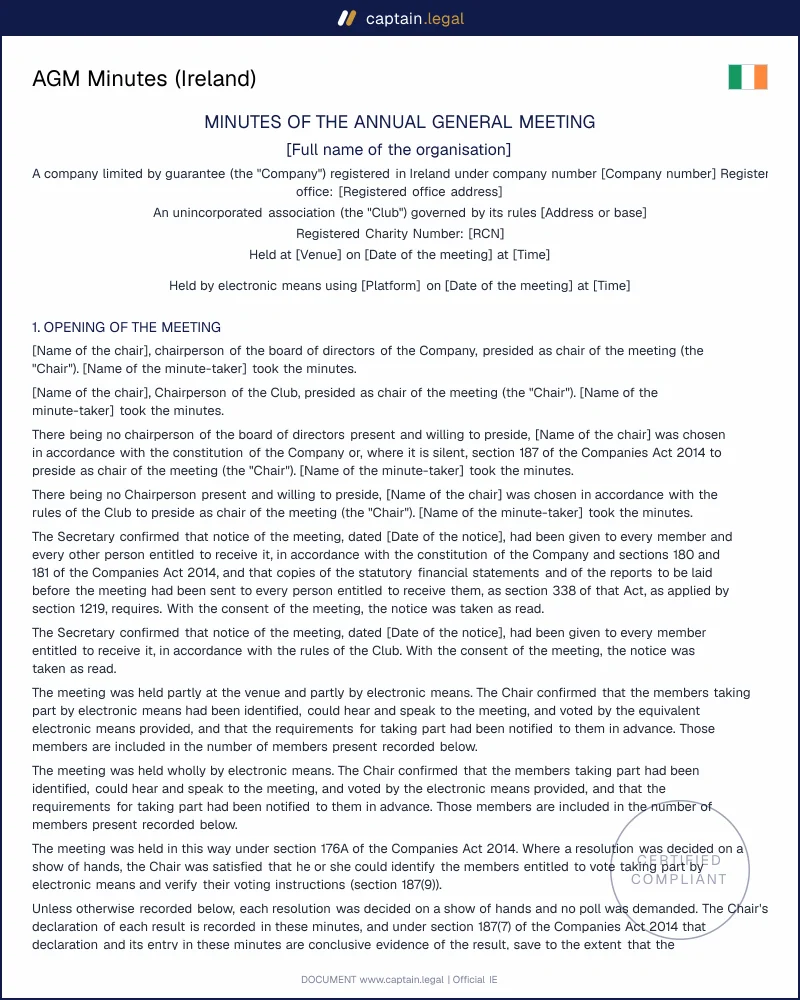
For a CLG, the governing statute is the Companies Act 2014, read with Part 18 on companies limited by guarantee. Section 175 requires an annual general meeting in each year, with no more than 15 months between one AGM and the next, and section 1202 prevents a CLG with more than one member from dispensing with it. Notice of at least 21 days is required under section 181, unless every member entitled to attend and vote, and any auditors, agree to shorter notice. The minutes themselves are governed by section 199, and the revised text of section 199 of the Companies Act 2014 sets out both the duty to keep the minute book and the evidential value of a signed minute.
Voting rules matter just as much. Under section 187(7), the chair's declaration that a resolution was carried on a show of hands, once entered in the minutes, is conclusive evidence of the result unless the constitution says otherwise. A special resolution needs not less than 75 per cent of the votes cast (section 191), and a copy must reach the Registrar of Companies within 15 days of being passed (section 198, applied to CLGs by section 1209). Directors retire under section 1196, all of them at the first AGM and one third at each later meeting, unless the constitution provides otherwise, and any change among the directors must be notified within 14 days (section 149(8)). Retiring auditors are deemed re-appointed under section 383(2) unless they decline, are not qualified, or the meeting resolves otherwise on extended notice.
A unanimous written resolution under section 193 can replace a vote, but majority written resolutions do not apply to CLGs, and neither route excuses a multi-member CLG from its AGM. Clubs answer to their own rules, while a registered charity must also file an annual report with the Charities Regulator within 10 months of its year end (section 52 of the Charities Act 2009).